High-Balance Jumbo Financing Mechanics in Coastal Orange County Markets
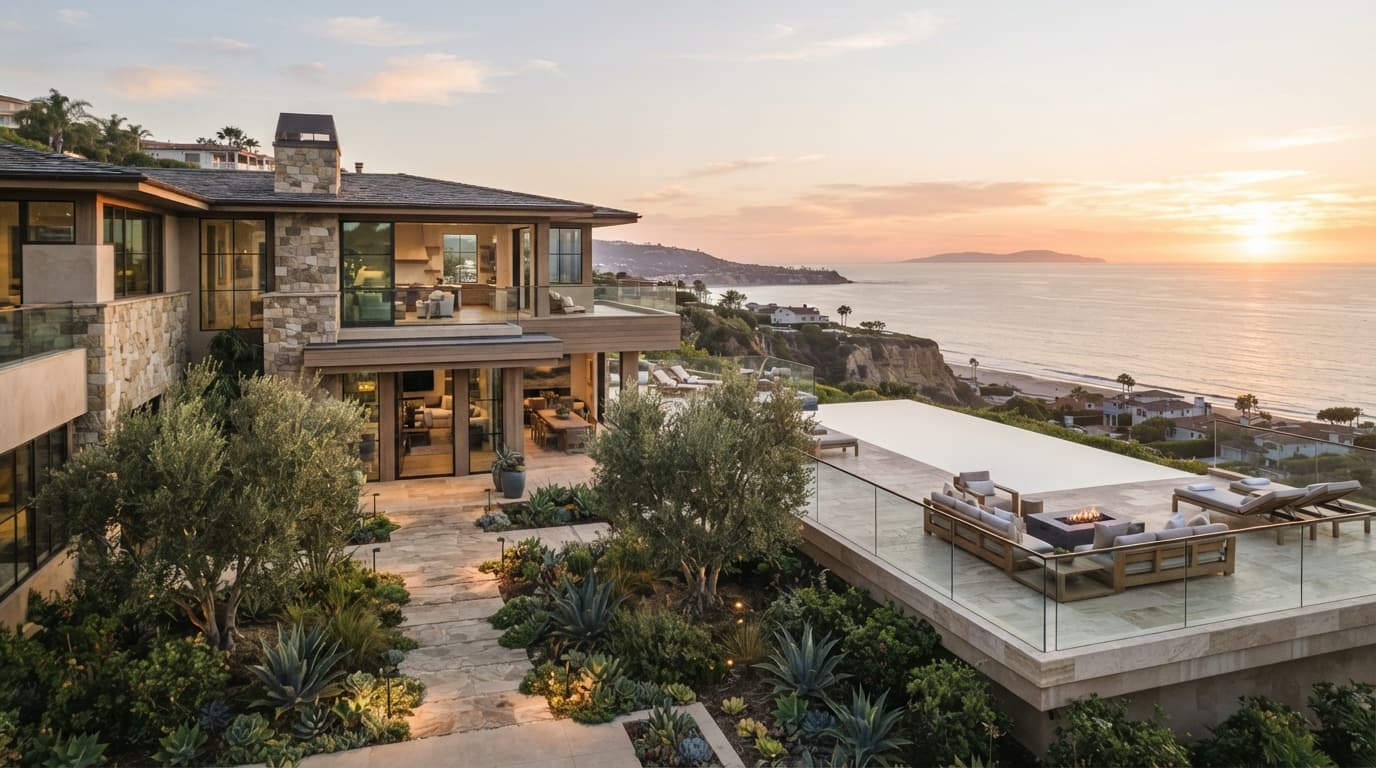
Coastal Orange County has some of the most distinctive housing in California, and many of its homes sit above standard loan limits. If you are shopping luxury properties near the water, understanding how high-balance and jumbo financing works can save you surprises later in the process.
High-Balance vs. Jumbo: What Is the Difference?
A conforming loan stays within the limits set each year for your county. A high-balance loan covers amounts above the baseline conforming limit but within the higher limit allowed for expensive counties, which can include Orange County. A jumbo loan goes beyond that ceiling entirely. The distinction matters because each category has its own guidelines for down payment, reserves, and credit.
Because rules change, check the current limits rather than trusting an article, including this one. We can confirm what applies to your purchase price on a quick call.
What Lenders Typically Look For
Larger loan amounts mean larger risk for the investor, so underwriting tends to be more detailed. Expect questions around:
- Down payment: often higher than for smaller loans, though programs differ.
- Reserves: many lenders want several months of payments in liquid assets after closing.
- Credit and debt ratios: stronger profiles generally open more options.
- Income documentation: salaried, self-employed, and business owners may follow different paths, including non-QM programs for complex files.
- Appraisal: high-value homes may need a more experienced appraiser and tighter comparable sales.
Why the Wholesale Channel Helps at This Price Level
Jumbo guidelines vary a lot from one lender to the next. One may allow a particular reserve structure or income type that another will not. As a wholesale broker, Century Financial Group Co. can access 45+ competing lending institutions and compare conventional, high-balance, jumbo, and non-QM options side by side. A retail bank generally offers its own single corporate rate sheet and its own guidelines. Neither approach is right for every borrower, but comparison gives you leverage.
An Example Payment Picture
This is an illustrative example with round numbers, not a quote. Say you are considering a $1,500,000 home with a 20% down payment, leaving a $1,200,000 loan. Your monthly cost is more than principal and interest. It also includes property taxes, homeowners insurance, possibly HOA dues, and sometimes flood or earthquake coverage depending on the location. Small differences in rate or loan structure can shift the monthly payment meaningfully at this size, which is why testing scenarios before you make an offer is wise. Rates and terms vary, subject to qualification.
Also remember that insurance can be a bigger line item on coastal and view properties, and lenders will want proof of adequate coverage before closing. Ask your insurance agent for quotes early so the payment you plan around is realistic.
Planning Your Coastal Purchase
Luxury buyers often compete with cash offers and with each other. A tidy plan helps:
- Decide your comfortable monthly payment, not just your maximum approval.
- Gather two years of income documents and recent asset statements.
- Run several down payment scenarios to see how each changes your payment.
- Get pre-approved before touring so your offer is taken seriously.
- Ask about timeline. Our marketed average is 18 days to clear-to-close, typically 14 to 21 days, compared with the 30-45 days common at retail banks.
Buyers coming from Irvine, Westminster, or Garden Grove sometimes move up to coastal addresses for lifestyle reasons such as proximity to the water, commute routes, or lot size. Whatever draws you, the financing math should come first.
Next Step
Use our Interactive Payment Estimator to test different purchase prices, down payments, and loan structures in a few minutes and see how they might change your monthly picture. When you are ready for specifics, call or text Hieu at (714) 627-5815, seven days a week. Our Bolsa Avenue office in Midway City carries a 5.0-star rating and 350+ aggregate 5-star client reviews, and bilingual support is available.
This article is for educational purposes only and is not a commitment to lend. Loan programs, rates, and terms vary and are subject to credit approval and qualification.
- #jumbo loan
- #high-balance loan
- #luxury homes
- #Orange County
- #coastal real estate
- #mortgage broker
Ready to review your options?
Get a personalized rate quote from Hieu Nguyen, or compare loan options.
This article is general education, not financial, tax, or legal advice, and is not an offer to lend. Rates and programs change; all loans are subject to credit and underwriting approval. Equal Housing Opportunity. See disclosures.